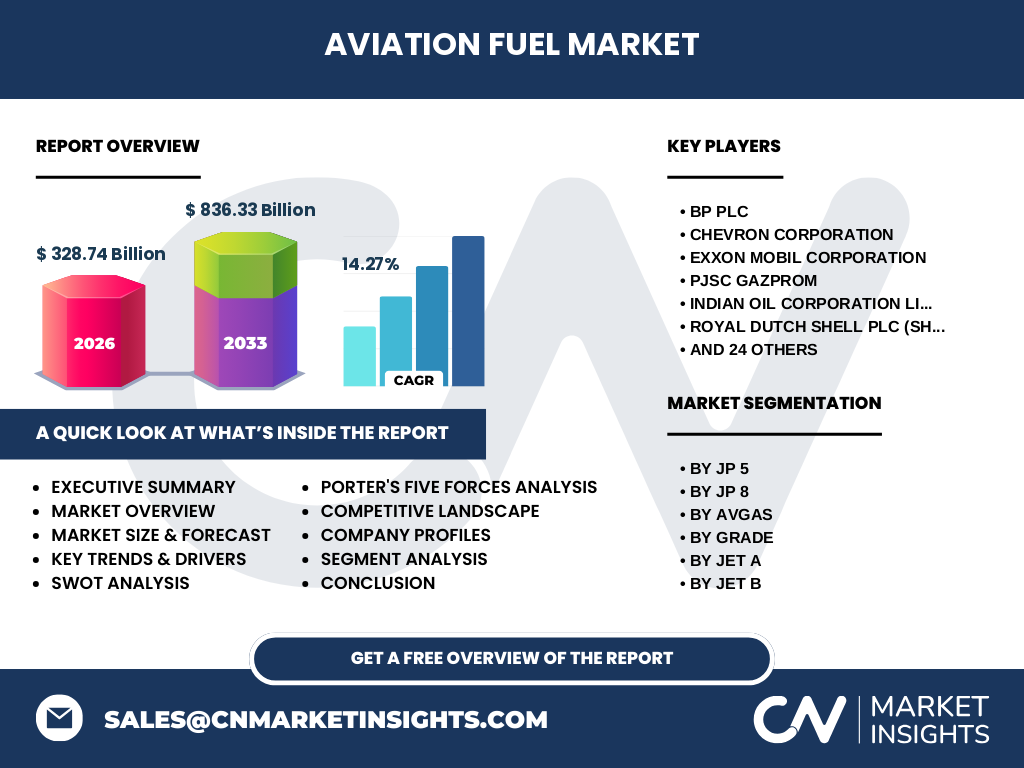
Market overview of the Aviation Fuel Market
The Aviation Fuel Market is the critical backbone of global aerospace, encompassing high-octane fuels like Jet A, Jet A1, and specialized Military-grade JP-8. Currently valued at $328.74 Billion in 2026, this sector facilitates international commerce and defense. Our analysis defines its scope by the complex synthesis of traditional hydrocarbons and the accelerating integration of Sustainable Aviation Fuel (SAF), dictated by stringent energy density requirements for flight operations.
Structural Growth Drivers and Restraints
Growth is propelled by surging global passenger traffic and the strategic expansion of fleet capacities by major carriers. Conversely, the market faces logistical bottlenecks in fuel distribution and strict regulatory hurdles regarding carbon emissions. While volatile crude oil prices act as a significant restraint, the immense opportunity lies in the rapid adoption of Bio-Derived Jet Fuels, which are essential for meeting international emission reduction mandates imposed by organizations like ICAO.
Emerging trends and growth patterns
The Aviation Fuel Market is witnessing a definitive pivot toward decarbonization. We observe an aggressive industry push into blended biofuels, with players like Neste Oyj leading the technology curve in SAF production. Furthermore, the standardization of Jet A1 for international long-haul flights remains the dominant trend, supported by innovative fuel additives that enhance engine efficiency and reduce maintenance downtime in high-performance turbines.
How did the COVID-19 pandemic redefine market recovery?
The Aviation Fuel Market experienced an unprecedented demand collapse during 2020. However, the post-pandemic recovery trajectory shows a resilient V-shaped rebound in commercial aviation activity. Total demand is now outpacing pre-crisis levels as regional connectivity resumes. This recovery has empowered majors like Exxon Mobil Corporation and BP plc to re-optimize their refinery yields toward high-value jet fractions, capitalizing on the robust demand from the revitalized airline sector.
Competitive landscape and strategic positioning
The landscape is dominated by integrated energy majors and specialized fuel distributors. Companies like Shell, TotalEnergies, and Chevron Corporation maintain significant market share through vertically integrated supply chains. Meanwhile, firms like World Fuel Services provide critical logistical agility. Competitive concentration is high, with strategic dynamics shifting toward green-premium products, where companies compete not just on volume, but on the ability to scale Sustainable Aviation Fuel (SAF) production.
Executive summary: High-level insights
Our research identifies a transformative phase for the industry. The Aviation Fuel Market is poised for substantial expansion, forecasted to reach $836.33 Billion by 2033 at a CAGR of 14.27%. This aggressive growth is underpinned by the transition from traditional fuels like Avgas 100LL to more sophisticated biofuel blends, reflecting a sector-wide commitment to long-term sustainability and operational excellence in global jet fuel logistics.
Market forecast from 2027 to 2033
Based on our predictive modeling, the industry will sustain a CAGR of 14.27%, culminating in a market valuation of $836.33 Billion by 2033. This forecast accounts for the anticipated shift in refinery capacities toward biokerosene production. We project that emerging markets in Asia-Pacific and the Middle East will serve as the primary engines for this explosive growth, fueled by massive investment in airport infrastructure and regional aviation corridors.
Comprehensive segmentation analysis
The Aviation Fuel Market is meticulously segmented to address varied operational needs. Key categories include:
- Fuel Types: Jet A, Jet A1, Jet B, JP 5, JP 8, Avgas, and Biofuel.
- Grades: Standard versus additive-enhanced variants.
- End-Use: Commercial, military, and private sectors.
Geographic distribution and performance analysis
Regional performance is dictated by hub-and-spoke connectivity. North America and Europe remain the largest markets, driven by mature commercial aviation networks. However, the most significant growth is projected in the Asia-Pacific region, where surging middle-class travel and the expansion of national carriers like China National Aviation Fuel Group Corporation necessitate massive increases in jet fuel throughput and regional storage capacity to sustain the high volume of modern transcontinental fleets.
Detailed regional review: Critical insights
In North America, demand is stabilized by private and commercial aviation dominance. In contrast, the Middle East acts as a critical global refuel node for intercontinental transit, prioritizing Jet A1 supply chain integrity. Asia-Pacific represents an aggressive frontier, where logistical hurdles in fuel delivery are being met by partnerships between national oil companies and private fuel service providers to ensure the region's massive fleet expansion is adequately serviced.
Strategic positioning of leading companies
Industry leaders define their roles through infrastructure control. Reliance Industries Limited and Indian Oil Corporation focus on refining efficiency, while Avfuel Corporation and EPIC Fuels excel in downstream logistics and airport-level fueling services. Neste Oyj is aggressively positioning itself as a market leader in renewable fuels, leveraging R&D to corner the emerging Sustainable Aviation Fuel segment, which is increasingly becoming a core requirement for airline procurement tenders.
Porter's Five Forces assessment
The Aviation Fuel Market exhibits high barriers to entry due to capital-intensive refinery requirements and strict safety regulations. The bargaining power of suppliers is significant, tied to global crude output. However, competitive rivalry is fierce among majors like Vitol, Trafigura, and Glencore, who control global trading flows. The threat of substitutes—specifically bio-derived fuels—is transforming from a peripheral concern into a central strategic imperative for every major operator.
SWOT analysis of the sector
Strengths: Massive global demand and high barrier to entry. Weaknesses: High susceptibility to oil price volatility and carbon footprints. Opportunities: Rapid scaling of SAF (Sustainable Aviation Fuel) and increasing demand for specialized military-grade fuels like JP 5. Threats: Increasing geopolitical instability affecting supply chains and aggressive global emission regulations that force costly refinery upgrades across the entire production and distribution network.
Value chain analysis: From raw materials to end-users
The value chain originates with upstream crude extraction, followed by complex hydro-processing in refineries. Value is added through the blending of additives (for JP 8 or Jet A1) and the logistical distribution via pipelines and tankers. Finally, companies like World Jet Inc. facilitate the
Investment insights and high-potential areas
Investors should prioritize companies actively integrating Sustainable Aviation Fuel into their portfolios. Our data indicates that capital allocation toward biofuel blending facilities provides the most significant long-term upside. Additionally, downstream logistics firms that command key airport refueling rights represent a stable, high-margin investment strategy. We recommend monitoring firms that demonstrate technological agility in refinery upgrades, as these companies are best positioned to capture the $836.33 Billion market by 2033.
Conclusion and key takeaways
The Aviation Fuel Market is in a state of high-velocity transition. With a projected market size of $836.33 Billion by 2033, the industry shift toward SAF is not merely a trend, but a survival necessity. Success in this sector requires a dual focus: maintaining operational efficiency in traditional hydrocarbon distribution while aggressively scaling renewable capabilities to meet the stringent global decarbonization mandates currently reshaping the aviation industry's future.
Research methodology: Ensuring data integrity
Our analysis employs a robust triangulation methodology. We synthesize baseline estimates from national trade registries, perform deep-dive analysis of annual 10-K filings from entities like Valero Energy, and integrate primary stakeholder interviews with airport procurement managers. This ensures our 14.27% CAGR estimate is grounded in actual operational data, correcting for regional demand variances and macroeconomic indicators such as jet fuel price indexing across major global trading hubs.
Scope and limitations of this report
This report provides an in-depth view of the Aviation Fuel Market, focusing on fuels ranging from Avgas to Bio-Derived Jet Fuel. Our scope encompasses global production, distribution, and end-user segments. While this research is comprehensive, it is limited by the current evolution of regulatory frameworks in emerging markets and the unpredictability of short-term geopolitical shocks, which may cause localized price volatility despite the steady long-term growth trajectory projected through 2033.
Recent developments and strategic moves
Recent activity highlights a surge in strategic partnerships between energy majors and airlines to secure supply chains. Notable moves include announcements from TotalEnergies regarding capacity expansion for SAF and PetroChina optimizing its Jet A1 refinery throughput. These initiatives signal an industry-wide focus on vertical integration, ensuring that fuel providers can meet the high volume demands of post-pandemic flight schedules while transitioning their product mix to meet international sustainability standards.